Every Annuity Lead We Sell Has To Get Past Us First.
In Business Since 2010
Over 3,000 Clients Served
Scott Brooks, MBA, CFP®
Here are 9 things we do differently.
#1. We Understand the Annuity Business.
Our founder, Scott Brooks, MBA, CFP®, began working in the financial industry in 1998. We understand annuities, the people who buy them, and what agents and advisors want from a lead.
#2. We’ve Been Doing This Since 2010.
Over 3,000 insurance agencies and financial advisory firms have purchased our leads. We’ve spent years testing, learning, and improving how we generate annuity prospects.
#3. We Don’t Rely on Just One Source.
We’ve generated annuity leads through multiple forms of advertising, including radio, television and online campaigns.
#4. No Long-Term Contracts.
Our annuity leads are exclusive, and you aren’t locked into a long-term contract. Daily and monthly caps let you control how many leads you receive.
#5. We Don’t Sell Every Lead We Generate.
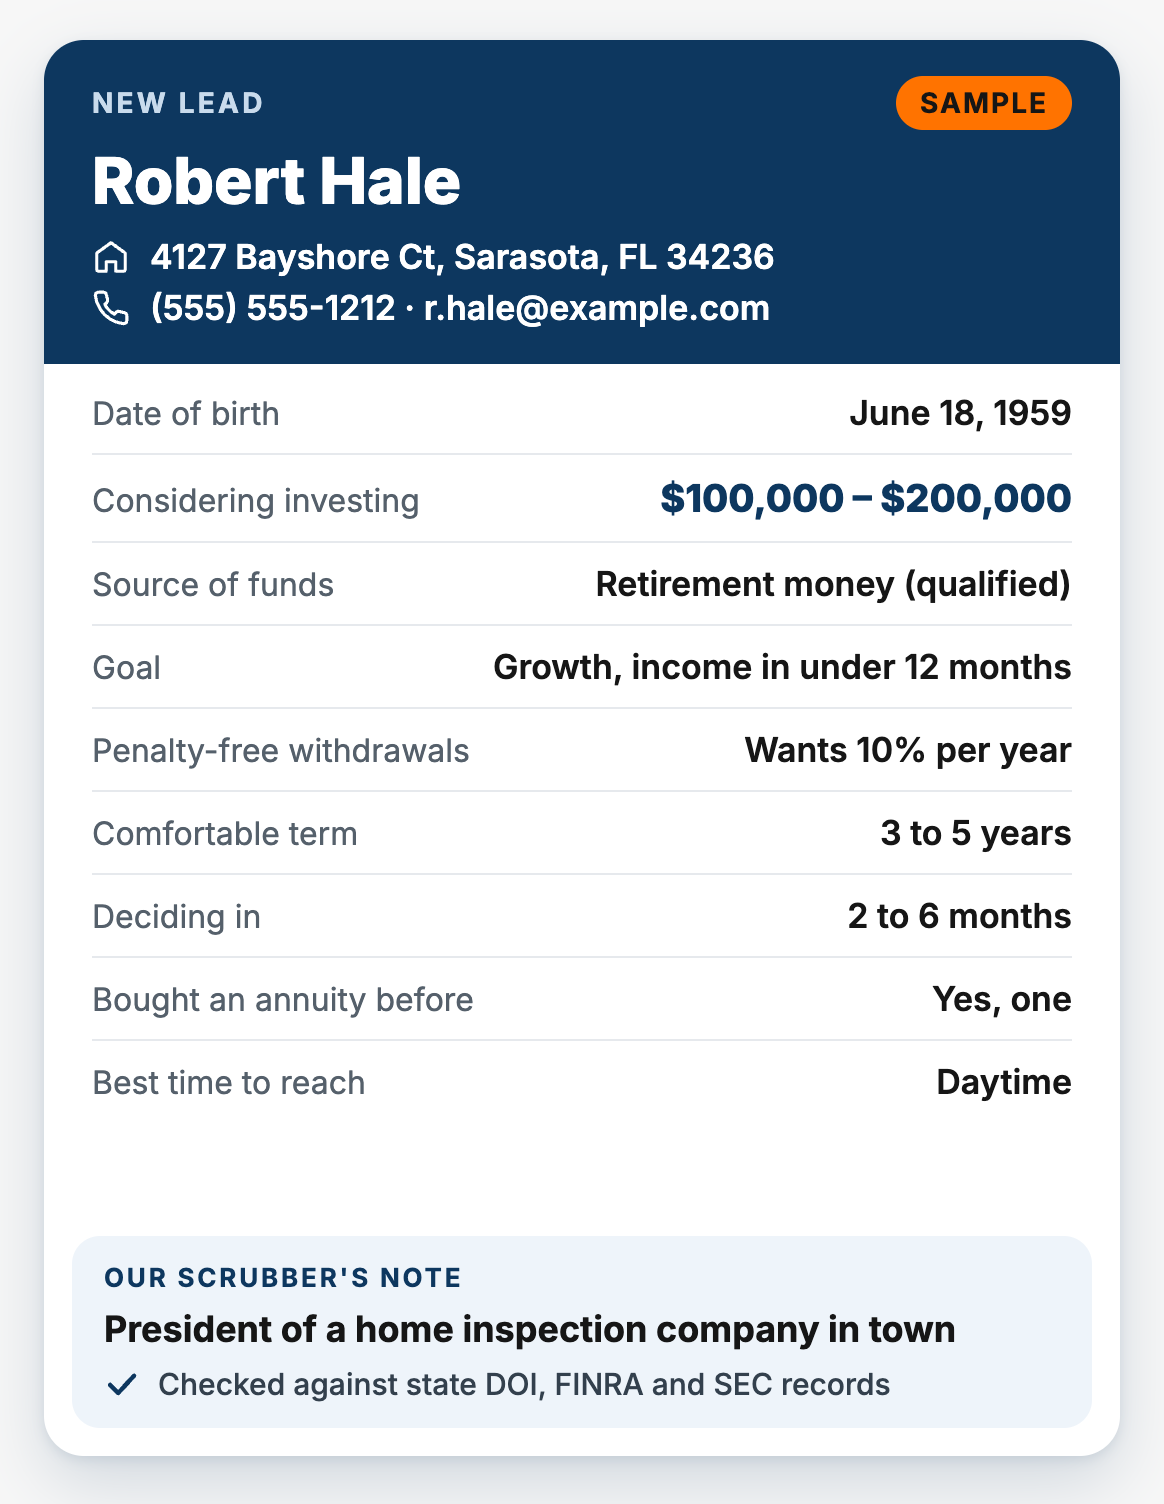
Generating a lead is only the beginning. Our team scrubs and verifies leads before they’re sold. Because what we reject can be just as important as what we send you.
#6. Our Business Was Built on Referrals.
Historically, about 90% of our clients have come from referrals from other clients and FMOs. You don’t build that kind of referral business without taking care of people.
#7. We Don’t Want Your Contracts.
We’re not an FMO or IMO using leads to recruit agents. Buy leads from us and keep your carrier relationships where they are. Our job is to generate annuity prospects—not reorganize your business.
#8. Our Annuity Leads Come From Annuity Advertising.
The people we send you responded to advertising about annuities. We don’t believe in attracting someone with an unrelated offer and turning that person into an “annuity lead.”
#9. We Don’t Use Too-Good-to-Be-True Promises to Generate Leads.
We believe the advertising used to create a lead matters. Our campaigns don’t rely on misleading 7–20% rates of return or income claims to get consumers to respond.
Common Questions
Answers to 38 of the most common questions we receive.
I’ve spoken to over 10,000 agents and advisors since 2010. Here are the 38 questions everyone asks about our lead program.
Scott Brooks, MBA, CFP®
President at TheAnnuityLeads.com
First and foremost, we understand what you want in an annuity lead. Because Scott is a CFP® who began in the industry in 1998, he knows the products, the industry, and how to create and scrub a high-quality annuity lead.
Most of our annuity leads today come from online campaigns. Over the years, we’ve also used radio, television, and other media, and the mix changes based on what performs.
Whatever the medium, every lead responds to advertising about annuities, and our campaigns are written to reach people with money to invest. We’ve always been selective about where we advertise.
We don’t judge a campaign by the number of responses it produces. We judge it by whether it creates leads from the kind of people our clients want to get in front of.
We try to reach upper-income baby boomers and seniors with assets. This is important because 50-60% of Americans have virtually nothing saved for retirement and have little to put aside into any retirement product. We believe the leads must have money to invest and be interested in annuities specifically for them to add value to your practice. Our leads have been exclusive since January 2010 and have never sold shared leads.
For Radio & TV, our average age is 64.
Online, our average age is 61
Yes. You should never purchase leads from a company unless they allow you to cap your account. We enable our clients to set both a daily and a monthly cap. When the monthly cap is reached, our software automatically shuts off client accounts and resumes the lead flow on the first day of the next month.
Testimonials
What Our Clients Are Saying About Us
“5 Appointments and $1,000,000 Closed From 12 Leads”
~ Belinda Royer, Charlotte, NC
“A Doctor Rescheduled Surgery to Finish Our Call”
~ Tom Beinar, San Francisco, CA
“A $7 Million Case. $2.5 Million Closed”
~ Mark Smith, Fort Worth, TX
“Two Cases Closed at $25,000 Commission Each”
~ Dan Blair, Denver, CO
“$1,372,213 Closed From One of the First Leads”
~ Dana Trenchfield, Pembroke Pines, FL
“$11,000 Invested. $3,000,000 In Production In 11 Months. “
~ Michael Watkins, Dunedin, FL
“$1,150,000 in New Premium From 15 Leads”
~ Josh Tschirgi, West Linn, OR
“Appointments on 5 of My First 7 Leads”
~ Jeremy Wood, Salt Lake City, UT
How We Scrub & Qualify Leads
Don’t Just Ask How a Lead Company Generates Leads. Ask How They Disqualify Them.
Every lead company can tell you how they generate leads.
We think there’s another question worth asking:
What happens after the consumer responds—and before the lead reaches you?
Our team scrubs and verifies annuity leads before they’re sold. See what we check, what we look for, and what can cause a lead to be rejected.
Founder Interview
Your Lead Company Makes Your First Impression Before You Ever Pick Up The Phone.
Its ads, its promises and its standards shape what a prospect thinks before you ever dial.
Almost every lead company will tell you its leads are exclusive, verified or pre-qualified. Those words only tell you so much. I think it also matters who’s running the company, how they generate the leads and what they’ve learned along the way.
I’m Scott Brooks, MBA, CFP®. I’ve been in financial services since 1998 and started selling leads to financial professionals in 2010.
Here’s how I got here, some of the mistakes I’ve made along the way, and what spending over 8 figures of annuity advertising has taught me.
Read the Founder Interview